Macro Cycle
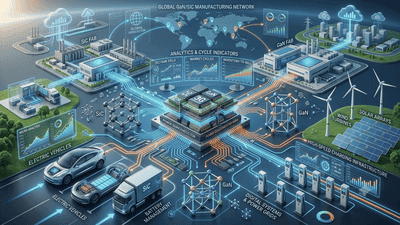
SiC and GaN 3rd-Gen Semi Penetration Rates Breach the Tipping Point
For years, silicon carbide (SiC) and gallium nitride (GaN) were discussed as promising “next‑generation” power semiconductor materials with clear technical advantages but limited commercial deployment. Their adoption curves were slow, constrained by cost, supply chain maturity, and conservative design practices in automotive and industrial markets.
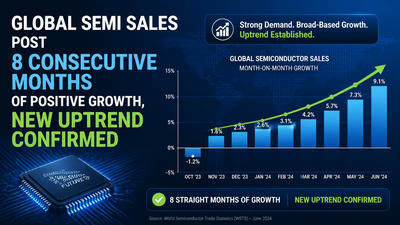
Global Semi Sales Post 8 Consecutive Months of Positive Growth, New Uptrend Confirmed
The semiconductor industry has crossed a meaningful threshold: eight consecutive months of positive year‑over‑year sales growth. That streak signals more than a short-term rebound. It suggests a structural rebalancing between demand and supply, improved capital discipline across the value chain, and the emergence of durable demand drivers that could support a multi‑quarter uptrend. For investors, OEMs, procurement teams, engineers, and policymakers, this turning point requires a shift in tactics—from defensive cost control and aggressive destocking toward selective restocking, targeted investment, and technology prioritization. This article examines why eight months matters, what’s driving the recovery, which subsegments will benefit most, the risks that remain, and practical actions stakeholders can take now.

Reassessing Global Semi Overcapacity Risks: A 2027 Outlook
Semiconductor capacity is expanding at a pace the industry has rarely seen. From large-scale fab projects in the United States and Europe to continued investments across Asia, the global wafer and packaging footprint heading into 2027 looks very different from what it was just a few years ago.
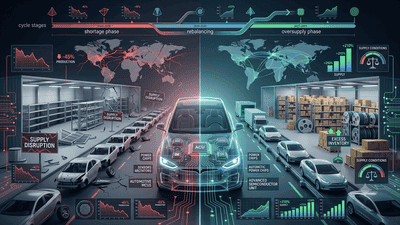
Auto Chip Supply-Demand Reversal: From Extreme Shortage to Structural Surplus
Only a few years ago, automakers around the world were halting production lines because they could not secure enough chips. Waiting lists for vehicles stretched out, component allocations were rationed, and procurement teams scrambled to find even small volumes of critical microcontrollers and power devices. Today, the picture looks very different. In multiple auto chip categories, supply has not just caught up with demand—it has overshot. What was once an extreme shortage is increasingly turning into a structural surplus.

QoQ Revenue Growth Ranking of Global Top 10 Semiconductor Firms
Quarter‑on‑quarter (QoQ) revenue growth for the world’s largest semiconductor firms offers a fast, quantitative snapshot of who is winning incremental demand at any given point in the cycle. It does not tell the whole story of structural strength, but it shows where momentum is moving in the near term—whether toward AI accelerators and advanced nodes, toward memory and storage, or toward analog and power devices tied to autos and industrial markets.
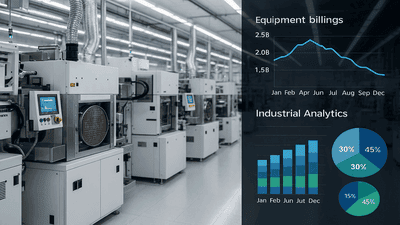
Leading Indicator: Interpreting North American Semi Equipment Billings
North American semiconductor equipment billings are one of the industry’s most watched data points. They capture how much chipmakers are actually spending on tools—lithography systems, etch and deposition equipment, inspection and metrology gear, and packaging machines—to build and upgrade fabs.
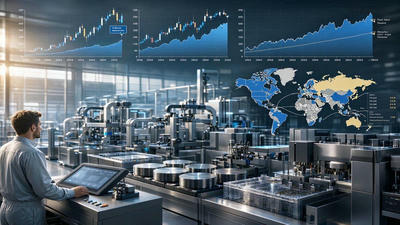
Using TSMC Monthly Revenue as a Bellwether for Global Semi Cycle Inflections
In the modern semiconductor industry, no single data point attracts more regular attention from market watchers than the monthly revenue disclosure of Taiwan Semiconductor Manufacturing Company (TSMC). Month after month, this one series of numbers sparks commentary about where the chip cycle stands, how demand for advanced nodes is evolving, and what lies ahead for everything from smartphones and PCs to AI infrastructure and automotive electronics.
Tracking CHIPS Act Subsidy Disbursements: Which Companies Have Received Funds?
The CHIPS and Science Act has moved from legislation on paper to money on the table. Passed in 2022, it earmarks tens of billions of dollars in subsidies and tax incentives to rebuild U.S. semiconductor manufacturing, advanced packaging, and upstream supply chains, alongside new support for emerging domains such as quantum computing.
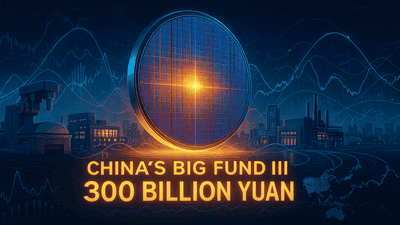
Big Fund III’s 300B Yuan Allocation: Equipment, Materials, and HBM Breakdown
China’s third national semiconductor investment vehicle—commonly referred to as “Big Fund III”—marks a new phase in the country’s effort to build a more self‑sufficient and globally competitive chip ecosystem. With a planned war chest on the order of 300 billion yuan, the fund is widely expected to pivot from simply backing wafer capacity toward deeper, more targeted investments in equipment, materials, and memory technologies such as high‑bandwidth memory (HBM).